Mastering the Balance: A Strategic Framework for Reliable, Risk-Aligned Maintenance Budgeting

By Owe Forsberg, CAMA, CMRP, VP of Consulting, TRM
Published: September 29, 2026
Executive Summary: The Maintenance Leadership Crucible
For industrial plant managers and maintenance supervisors, few challenges are as universally daunting—or as critical to career longevity—as managing and defending the maintenance and reliability (M&R) budget. Too often viewed by upper management as a static cost center rather than a strategic driver of operational stability, the maintenance budget becomes the prime target for arbitrary cuts.
In heavy manufacturing, biochemical facilities, and process industries, an ill-considered budget reduction can trigger a cascade of deferred maintenance, accelerated asset degradation, catastrophic equipment failures, and compromised safety standards.
Effective maintenance budgeting transcends basic accounting. It is a rigorous, multidisciplinary planning process that directly impacts plant availability, safety profiles, environmental compliance, and long-term profitability. Building a sustainable M&R budget requires moving away from historical assumptions and lazy "across-the-board" percentage cuts. Instead, industry leaders must embrace activity-based budgeting, transparent risk analyses, cross-functional accountability between maintenance and operations, and a clear distinction between routine upkeep and major capital overhauls.
Chronology of a Leadership Challenge: Navigating the Budget Gap
Years ago, while working as a maintenance supervisor in a complex biochemical processing plant, I was summoned to the office of the Operations Vice President. The meeting opened with a direct, high-stakes question: "Do you want to be the maintenance manager?"
"Of course," I responded, stepping eagerly toward the next phase of my leadership career.
The Vice President’s directive was immediate and sobering: I needed to get the plant’s maintenance budget under control. Because we were only in the second month of the fiscal budget year, I initially assumed the variance could not be overly severe. However, a deep dive into the financial ledgers revealed an alarming reality. My predecessor had failed to budget for five full-time maintenance craftspeople. Furthermore, the plant was critically underfunded for vital external services and specialized contractor support.
As seasoned industrial managers know all too well, cutting a maintenance budget under duress is one of the most perilous leadership trials an individual can face. It requires immediate, deliberate alignment starting from within the maintenance organization itself.
Confronting the Team and Restructuring the Data
My first staff meeting as incoming maintenance manager was exceptionally tense. Maintenance supervisors and reliability engineers were visibly frustrated; the newly uncovered budget gap fundamentally disrupted their planned schedules and routine work execution strategies.
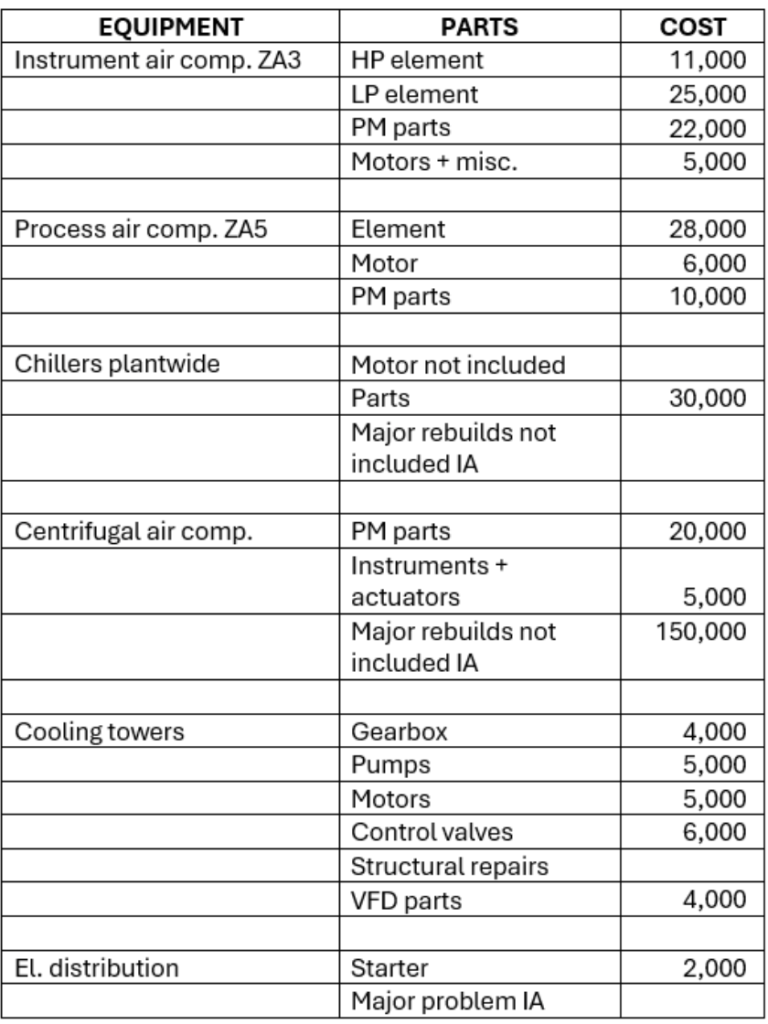
Still, emotional reactions could not alter the financial balance sheet. To manage the budget responsibly, we needed granular data. The team ultimately agreed to halt defensive posturing and begin gathering historical spending metrics. Our core objective was clear: analyze actual expenditures over the previous several years and construct a bottom-up, activity-based budget.
We systematically categorized our financial obligations, breaking down spending by functional locations, asset classes, and specific operational requirements—ranging from routine parts repair to specialized contractor services.
Chronology: Facing the 3% Additional Cut and Standing Firm
With exceptional analytical support from our planning supervisor and the plant finance team, we meticulously documented every spending category. This foundational work provided a crystal-clear view of the specific activities, true labor costs, parts utilization rates, and underlying operational assumptions driving our budget estimates.

Just as our financial plan began to stabilize, the leadership pressure intensified. A few months into the fiscal year, I was called back to the Vice President’s office and instructed to slash our operating budget by an additional 3%—on top of the massive shortfall already identified at the start of the year.
I prepared a series of strategic options and returned to the VP’s office. When I presented the available savings pathways, his response was curt and uncompromising: "I don’t care where you save the money—just meet the budget target."
I paused, recognizing that accepting an arbitrary cut without documented consequences would inevitably lead to finger-pointing when equipment inevitably failed later in the year.
"We need to agree on the specific savings actions right now," I countered, "so there is no ambiguity or blame at the end of the year."
"I’m not interested in the mechanics," he shot back. "It’s your job to find the savings."
"Understood," I replied calmly. "Here are the exact operational activities I will remove to hit your budget target, ranked strictly by lowest operational risk and asset criticality."
I walked him through the proposed list of deferrals: delaying non-critical preventive maintenance routines, postponing planned asset inspections, and cutting specific equipment upgrades.
He looked up from his desk, suddenly fully engaged. "That is entirely unacceptable, and you can leave my office now," he ordered.
I stood my ground. I informed him that I would not leave until we reached a mutual, documented consensus on which operational activities would be postponed, cancelled, or funded elsewhere. Eventually, the reality of the risk profile set in. We reached an explicit agreement: three non-critical activities would be deferred, and leadership would find alternative funding for critical Variable Frequency Drives (VFDs) within the broader operating budget.
As I turned to exit his office, I heard him mutter under his breath: "Ugh, you make this so difficult!" But the budget was secure, and more importantly, the risks were transparently understood.
Supporting Data and Cross-Functional Accountability
Later that operating year, a troubling behavioral pattern emerged: operating department managers were systematically pushing our maintenance technicians to prematurely replace components rather than repairing them. Naturally, the high cost of those wholesale replacements came straight out of the maintenance budget.
In asset management terms, this practice was deeply inefficient. Discarding components that still retained years of useful operating life—and which did not require major capital repair costs—made zero financial sense from a total cost of ownership perspective.
Bridging the Maintenance-Operations Divide
To eliminate this friction, I proposed a structural governance change to the Vice President and the plant management team: operations managers must share direct financial accountability for direct materials spending alongside the maintenance manager. Each operating unit would be held accountable for meeting its designated portion of the direct materials budget.
Once this shared accountability model took effect, the culture shifted immediately. Every single "repair-versus-replace" decision became subject to a rigorous cost-effectiveness review.
Simultaneously, the plant struggled with work prioritization across competing areas with different departmental stakeholders. Too often, maintenance resources were dispatched based on the "loudest voice" rather than the highest operational priority. To streamline decision-making, we restructured plant responsibilities around clear criteria, ensuring that minor additions and unauthorized plant upgrades could no longer drain maintenance dollars.
We established a strict rule: any equipment modifications or minor additions had to be approved by the department manager, and the owning department had to formally budget for them before work commenced. As the industrial adage dictates: Never spend money before you have it.
Managing Major Overhauls: Avoiding "Ballooning the Budget"
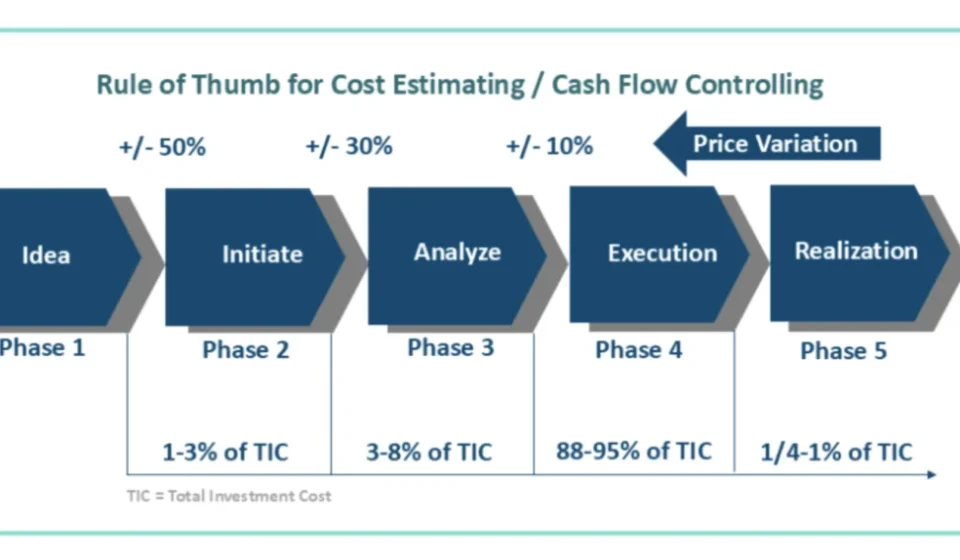
A persistent threat to maintenance financial stability is what I term "ballooning the budget." In many manufacturing plants, major overhauls and heavy equipment replacements are stealthily buried inside regular annual maintenance budgets.
For instance, a scheduled three-year overhaul of a massive, two-stage 2,000 HP centrifugal compressor can easily cost between $500,000 and $700,000. Outlays of this magnitude cause annual maintenance budgets to swing wildly by 10% to 15% from year to year, creating panic and forcing unwarranted cuts to routine upkeep.
Following extensive consultations with the finance department, we instituted a structural separation:
- Routine Operating Budget: Reserved strictly for annual upkeep, minor repairs, predictive monitoring, and regular preventive maintenance.
- Multi-Year Capital/Overhaul Plan: Major multi-year overhauls, major unit shutdowns, and end-of-life asset replacements were carved out into a distinct, forward-looking 3- to 5-year funding mechanism.
This separation stabilized annual operating spend and insulated routine maintenance from the violent financial shocks of heavy industrial overhauls.
Summary of Best Practices for Your M&R Budget Playbook
To achieve long-term asset reliability and financial control, industrial organizations should embed the following foundational principles into their maintenance management playbooks:
1. Build a Zero- or Activity-Based Budget
Do not simply index last year’s spending figures by an arbitrary percentage. Build your maintenance budget from the ground up every cycle. Every labor hour, replacement part, and contractor service must be justified by actual equipment criticality and planned operational workloads.
2. Differentiate Routine Maintenance from Major Overhauls
Separate yearly recurring maintenance from multi-year capital overhauls. Utilize a 3- to 5-year capital replacement plan for heavy assets (such as large compressors, turbines, and primary reactors) so funding is secured well in advance without cannibalizing routine daily upkeep.
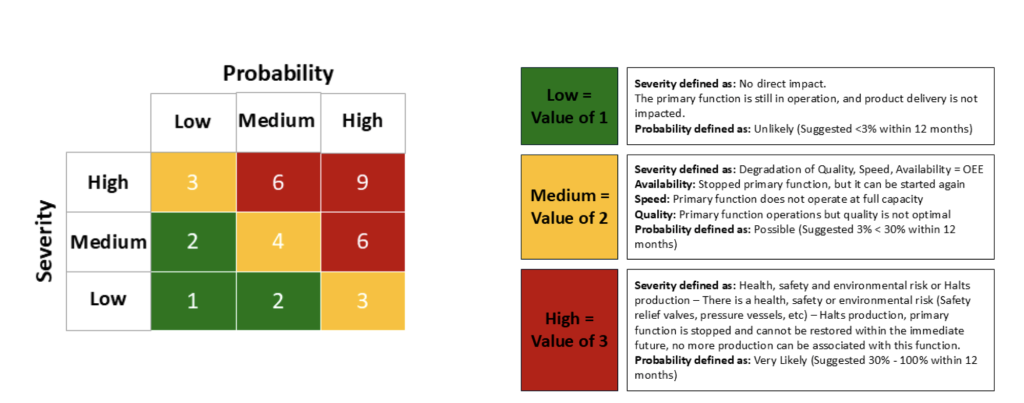
3. Align the Budget with Business Risk
Evaluate all budget activities through a formal risk matrix:
$$textRisk = textSeverity times textProbability$$
Involve cross-functional Subject Matter Experts (SMEs) from Maintenance, Operations, Engineering, Quality, and Finance to evaluate how budget cuts impact safety, environmental compliance, and throughput.
4. Enforce Cross-Functional Accountability
Charge maintenance materials and repair costs directly to the operating units. When operations managers share financial responsibility for direct materials and asset care, they transition from passive consumers of maintenance services to active strategic partners in asset health.
5. Protect the Maintenance Backlog
When budgets are squeezed, do not hide deferred work by deleting work orders. Keep all legitimate equipment defects in the Computerized Maintenance Management System (CMMS) backlog. A transparent backlog demonstrates the exact operational risks associated with budget reductions, giving plant leadership an unvarnished view of deferred liabilities.
Implications and the Road Ahead
Effective maintenance budgeting is much more than a routine financial exercise; it is a vital strategic planning discipline that directly dictates plant reliability, operational safety, and bottom-line profitability.
When maintenance leaders and plant executives stand together on principles of transparency, activity-based tracking, and risk-aligned decision-making, the entire industrial facility becomes safer, more stable, and structurally prepared for future market demands.
Partnering for Reliability Excellence
Across the process industries and heavy manufacturing sectors, organizations partner with firms like TRM to turn these theoretical frameworks into daily operational realities. TRM’s seasoned consultants combine deep maintenance engineering expertise with hands-on change management experience to help plants build robust activity-based budgets, strengthen cross-functional alignment, and optimize long-term asset performance.
Whether your facility is stabilizing an erratic operating budget, modernizing reliability workflows, or establishing a multi-year asset health roadmap, TRM provides the practical guidance and tactical support needed to drive measurable results.
Contact and Connect
- Inquiries: Contact TRM Senior Business Consultants at [email protected]
- Professional Network: Follow Owe Forsberg on LinkedIn for ongoing insights into industrial reliability, asset availability, and practical maintenance management.
- Resources: Access official guides and whitepapers at TRM Group.