
Navigating the Decade: A Comprehensive Analysis of General Motors’ Production Forecast to 2030

By Jonathan Storey
Automotive Industry Analyst
Main Facts
As the global automotive industry undergoes the most profound structural transformation in a century, legacy automakers are racing to redefine their market positions, supply chains, and manufacturing footprints. General Motors (GM), one of the world’s legacy automotive titans, stands at the center of this monumental shift. A newly released long-term production forecast by Automotive World maps out the trajectory of General Motors’ manufacturing output, market performance, and strategic pivots through the year 2030.
The analysis underscores several pivotal realities governing GM’s operational outlook over the remainder of the decade:
- The EV Transition Curve: GM’s production strategy is fundamentally anchored in its aggressive transition toward battery-electric vehicles (BEVs), underpinned by its proprietary Ultium battery architecture and Ultium Drive electric propulsion systems.
- ICE Profitability and Phase-Down: While capital expenditure and future-facing investments are heavily skewed toward electrification, GM continues to rely on the steady cash flows generated by its legacy internal combustion engine (ICE) truck and SUV portfolios—particularly in the North American market.
- Geographic Realignment: Production volumes are projected to experience shifts across key global regions, with a strong emphasis on localized battery and EV manufacturing in the United States, alongside complex navigation of the hyper-competitive Chinese automotive market.
- Supply Chain Resilience: The forecast highlights that GM’s long-term output will be heavily dictated by its ability to secure critical raw materials, localize rare-earth supply chains, and mitigate ongoing geopolitical and macroeconomic volatility.
Ultimately, the forecast illustrates a company walking a strategic tightrope: scaling up next-generation technologies fast enough to satisfy regulatory demands and shifting consumer preferences, while maintaining sufficient manufacturing output from traditional profit centers to fund the multi-billion-dollar transition.
Chronology: GM’s Path from Post-Pandemic Recovery to the 2030 Horizon
To understand where GM’s production volume is projected to land by 2030, it is vital to trace the chronological milestones that have shaped—and will continue to shape—the automaker’s manufacturing strategy during this decade.
2020–2022: The Pandemic Crucible and the Ultium Pivot
The dawn of the 2020s tested the operational resilience of every global automaker. General Motors was no exception, grappling with unprecedented semiconductor shortages, factory shutdowns, and logistics bottlenecks in the wake of the COVID-19 pandemic. However, this period also marked a profound strategic pivot.
- March 2020: GM hosted its EV Day, officially unveiling the Ultium battery platform, which promised modularity, scalability, and significantly lower battery pack costs.
- January 2021: In a landmark announcement, GM set a corporate target to eliminate tailpipe emissions from new light-duty vehicles by 2035, aiming for carbon neutrality by 2040.
- Late 2021–2022: Despite supply chain disruptions severely constricting total vehicle output, GM broke ground on multiple battery cell manufacturing joint ventures (Ultium Cells LLC) in states like Ohio, Tennessee, and Michigan.
2023–2025: Scaling Realities and Production Bottlenecks
The mid-2020s represent a phase of execution, friction, and recalibration for GM’s manufacturing operations.
- Throughout 2023: GM faced well-publicized production ramp-up challenges related to automated module assembly lines at its Ultium battery plants, which temporarily depressed the production volumes of early BEV models like the Cadillac Lyriq and GMC Hummer EV.
- Late 2023: A historic six-week strike by the United Auto Workers (UAW) union resulted in significant lost production days and a new, more costly master labor agreement. This contract fundamentally altered GM’s domestic cost structure and forced a re-evaluation of long-term labor productivity assumptions.
- 2024–2025: In response to slower-than-expected early consumer adoption curves for certain mass-market EVs and lingering consumer price sensitivity, GM adjusted its near-term EV production targets. The company reintroduced plug-in hybrid electric vehicle (PHEV) technology to its North American roadmap—a strategic hedge acknowledging that the transition to 100% BEVs would be non-linear. Simultaneously, high-margin full-size pickup trucks (Chevrolet Silverado and GMC Sierra) continued to anchor overall factory output and financial performance.
2026–2030: The Push Toward the Decade’s End
As GM moves into the second half of the decade, the forecast anticipates a period of stabilization and accelerated volume scaling.
- 2026–2028: Second- and third-generation Ultium architectures are slated to roll onto assembly lines, offering dramatic cost reductions (target of up to 40% lower battery costs) and improved energy densities. Factory floors across North America will undergo further retooling, shifting from mixed ICE/EV lines to dedicated EV manufacturing facilities.
- 2029–2030: By the close of the decade, the forecast projects that BEVs will account for a substantial majority of GM’s domestic production output. The legacy ICE portfolio will be heavily rationalized, leaving only high-demand, high-margin commercial and heavy-duty truck segments operating on liquid fuels in mature markets.
Supporting Data & Market Metrics
An analysis of General Motors’ production forecast requires a rigorous examination of the underlying data trends—covering capacity utilization, regional output distribution, and powertrain mix shifts.
Global Volume and Capacity Utilization
Historically, GM’s global production footprint has hovered between 5 million and 6 million units annually, a figure that includes equity joint ventures, particularly in China through SAIC-GM.
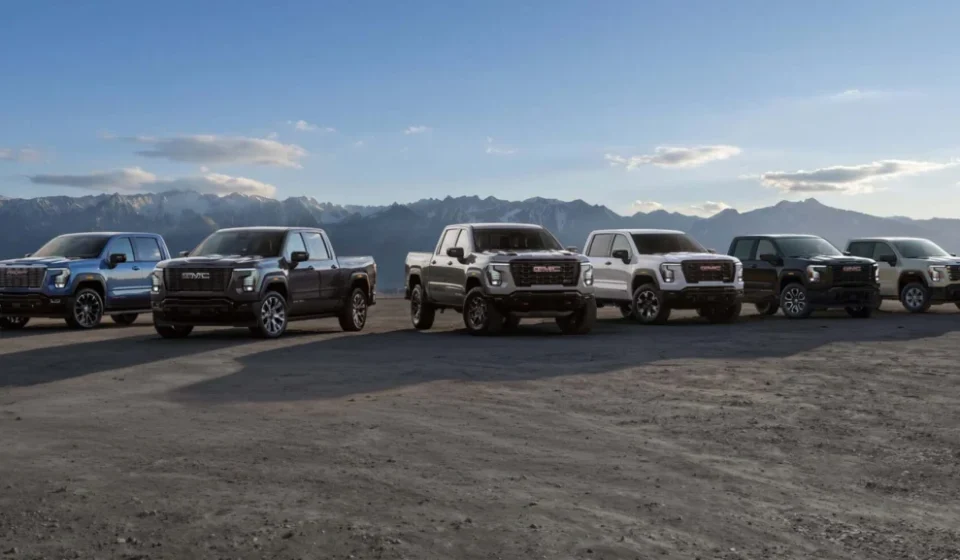
- The North American Anchor: North America remains the bedrock of GM’s manufacturing profitability. Plant capacity utilization in the United States and Mexico is projected to remain relatively high (ranging between 80% and 85%), driven by relentless consumer demand for full-size SUVs (Chevrolet Tahoe/Suburban, GMC Yukon, Cadillac Escalade) and light- and heavy-duty pickup trucks.
- The Chinese Market Realignment: In contrast, GM’s production volume in China—once the company’s largest volume market—has faced structural headwinds. The rapid ascent of domestic Chinese EV manufacturers (such as BYD, Geely, and a myriad of EV-native startups) combined with aggressive price wars has compressed GM’s market share and forced SAIC-GM to recalibrate factory footprints, emphasizing lower-cost local EVs and shifting away from declining foreign-branded ICE sedans.
Powertrain Transition Metrics (Projected to 2030)
| Metric / Indicator | 2022 (Actual) | 2025 (Estimated) | 2030 (Forecast) |
|---|---|---|---|
| Global BEV Output Share | ~3.5% | ~15–18% | ~55–65% |
| ICE Portfolio Weight | ~96.5% | ~82–85% | ~35–45% |
| Ultium-Based Plants (Cumulative) | 2 operational | 4–5 operational | 6+ fully integrated |
| Average Battery Pack Cost ($/kWh) | ~$135–$140 | ~$100–$110 | <$80 |
Supply Chain and Battery Economics
The data highlights that long-term production feasibility is inextricably tied to the per-kilowatt-hour cost of battery cells. GM’s joint venture with LG Energy Solution, alongside independent battery development partnerships, aims to drive cell-level costs down below the critical $80/kWh threshold by the late 2020s. Achieving this cost parity with legacy ICE vehicles is modeled as the primary catalyst enabling GM to scale BEV production profitably without relying indefinitely on regulatory credit sales or unsustainable government subsidies.
Official Responses and Strategic Perspectives
Executive leadership at General Motors, alongside industry analysts and union representatives, have offered varied perspectives on the operational realities shaping the road to 2030.
Corporate Leadership: Flexibility as a Strategic Imperative
In recent investor communications and earnings calls, GM Chief Executive Officer Mary Barra has repeatedly emphasized the concept of guided flexibility. While GM’s ultimate destination remains a fully electric portfolio, executive management has made it clear that manufacturing lines and capital deployment will remain adaptable to consumer demand rhythms.
"Our long-term commitment to an all-electric future is unchanged, but the path and timing of that transition will be guided by our customers, charging infrastructure development, and regulatory realities," Barra noted in a recent strategic briefing. "We have engineered our manufacturing ecosystem to pivot efficiently. Whether a customer wants a world-class internal combustion truck, a high-efficiency plug-in hybrid, or a long-range battery-electric vehicle, GM’s plants are designed to deliver."
Chief Financial Officer Paul Jacobson has similarly underscored that capital allocation through 2030 will prioritize disciplined return on invested capital (ROIC). Rather than chasing arbitrary volume targets at the expense of margins, GM’s production planning is built around maintaining profitability across every powertrain segment.
Labor and Workforce Perspectives
The United Auto Workers (UAW), fresh off the 2023 contract negotiations, maintains a watchful eye on GM’s production forecasts. Union leadership has consistently pressed the automaker to ensure that the transition to electric vehicle manufacturing—which inherently requires fewer direct labor hours per vehicle than legacy ICE assembly—does not result in net job losses or diminished wage standards.
The inclusion of battery manufacturing plants under master labor agreements has been a critical focal point. UAW officials stress that as GM phases down traditional engine and transmission plants over the remainder of the decade, workers must be retrained and transitioned into the battery and EV component supply chain with equivalent compensation and union representation.
Independent Industry Analysts
Automotive analysts tracking the Automotive World forecast point out that GM’s primary challenge is not manufacturing competence, but macroeconomic volatility. Analysts note that while GM’s vehicle architectures (such as Ultium and the upcoming modular software platform) are technologically robust, external factors—ranging from shifting federal tax policy incentives and trade tariffs to raw material price fluctuations—introduce significant variance into any 2030 production model.
Implications: What the 2030 Forecast Means for the Industry
The comprehensive outlook for General Motors through the end of the decade carries profound implications not just for the company itself, but for the broader automotive ecosystem, suppliers, consumers, and policy-makers.
1. The Transformation of the Supply Chain Ecosystem
Tier-1 and Tier-2 automotive suppliers face a high-stakes mandate. Companies that have traditionally supplied exhaust systems, fuel injection components, and complex multi-speed transmissions must rapidly pivot toward thermal management systems, power electronics, battery management software, and lightweight structural casting. The forecast indicates that by 2030, the traditional supplier ecosystem will look fundamentally unrecognizable, with supplier consolidation favoring those deeply integrated into the EV value chain.
2. Infrastructure Dependency as a Production Ceiling
One of the most critical takeaways from long-term forecasting is that automotive manufacturing output is no longer bounded solely by factory floor capacity or raw material availability, but by charging infrastructure deployment. If public and private DC fast-charging networks fail to scale in tandem with GM’s planned EV production increases, consumer adoption bottlenecks will inevitably force inventory build-ups, leading to scheduled production cuts and factory downtime.
3. Pricing Power and Margin Evolution
As EV production volumes scale toward the 2030 horizon, the economics of vehicle manufacturing will shift. Early-generation EVs have notoriously carried lower—or negative—profit margins compared to their ICE counterparts. GM’s ability to successfully execute its cost-reduction targets (through localized chemical sourcing, elimination of cobalt where possible, and streamlined structural designs) will determine whether the automaker can preserve its historical profit margins in a post-ICE world.
4. Geopolitical Vulnerabilities and Regionalization
The geopolitical landscape will continue to cast a long shadow over automotive manufacturing. With stringent regulatory requirements regarding domestic sourcing (such as those embedded in North American trade agreements and clean vehicle tax credits), GM is actively localized its supply chain—shifting away from heavy reliance on single-region sourcing for critical minerals like lithium, nickel, and graphite. The 2030 forecast assumes a more regionalized, resilient manufacturing model, insulating the company from overseas shipping disruptions and geopolitical trade disputes.
Conclusion
General Motors’ production forecast to 2030 captures a legacy industrial giant navigating a generational transition. The road ahead is defined by duality: the necessity of maximizing cash flow from a highly profitable, traditional internal combustion portfolio while simultaneously funding and scaling a clean-sheet electric vehicle manufacturing ecosystem.
As Automotive World’s analysis illustrates, GM’s ultimate success at the close of the decade will not be measured by total vehicle volume alone, but by strategic agility, supply chain resilience, and the sustained profitability of its next-generation product portfolio. For investors, workers, and consumers alike, the remaining years of this decade will determine whether General Motors successfully bridges the gap between its century-old industrial heritage and the high-tech electric future.